

Update — August 6, 2026: This essay received an honorarium in the Boyd Institute’s Debt and Deficits Essay Contest. In its announcement, Boyd highlighted the essay’s identification of “a real risk, tax receipts actually falling as output grows” and its “well-fleshed-out solution.” [Read the announcement here.]
The United States has a spending problem and a revenue problem both. It also has a third problem, underneath those two and priced by almost no one: a seeing problem.
Every serious fiscal plan in circulation is an argument about two levers. Spend less: reform entitlements, cap discretionary growth, means-test, raise the retirement age. Take more: lift rates, broaden the base, close loopholes, tax wealth. The debate is old and the positions are worn smooth. What almost no plan examines is the thing both levers depend on, the quiet assumption underneath the whole apparatus: that the state can still see income clearly enough to tax it.
Fiscal capacity begins there, with orientation, not with rates. Every act of taxation is downstream of an act of sight: you cannot claim what you cannot see, and you cannot see more clearly by looking harder at the wrong place. A state that loses track of where value forms does not just collect less. It loses the ability to act on the economy at all.
America escapes the fiscal trap by doing what it did once before: attaching the tax state to the dominant measurement layer of the economy. In the twentieth century, that layer was payroll. In the machine economy, it is compute. The policy is Federal Compute Withholding: a low, provider-side levy on large-scale AI training and inference, collected where machine output is already metered, and used dollar-for-dollar to reduce payroll taxes on human labor.
That is not a side payment to the existing tax system. It is a tax-base transition. If the machine economy is going to replace part of the wage economy, then the fiscal state has to move part of its sensor from wages to compute before the base learns to disappear.
For a century it could see. The reason was the wage.
Modern fiscal capacity did not grow out of a smarter tax code. It grew out of an accident of measurement. When income arrives as a wage, it arrives already visible. The employer computes it, reports it, and withholds against it before the worker ever touches the money. Payroll withholding turned the private economy into a machine that reports itself. The state did not have to chase most of its revenue. The revenue arrived pre-counted, at the source.
This is not a minor feature of the system. It is most of the system. In the United States, individual income and payroll taxes together supply roughly eighty-five percent of federal revenue [1]. Across the OECD, personal income tax and social contributions make up about half of all tax revenue [2]. Payroll was not just income. It was the reporting layer of industrial capitalism. The fiscal state is, structurally, a wage-reading instrument. Its power to fund itself is inseparable from labor income being the most legible thing in the economy.
This is legibility in James Scott’s sense: a state acts only on what it has first made readable. Scott’s modernizers made forests, land, and people legible in order to govern them. The fiscal state made the wage legible in order to tax it. The principle is old. Applying it to the tax base, and watching that base turn unreadable, is the new part.
That legibility is now migrating out from under it.
The base is leaving the sensor
The standard worry about automation is that fewer workers will pay less tax. The real problem is stranger and harder. As intelligent systems compress labor, value does not simply shrink. It moves. It accrues to capital, to equity, to the owners of compute, and increasingly to autonomous systems whose output has no wage line at all.
Capital income was always less legible than wages. It is harder to withhold, easier to shift across borders, and timed to the taxpayer’s convenience through the choice of when to realize a gain. Agentic output is worse still, because there is no employer in the loop to report it. A human employee produces a W-2. A model produces output. An agent completes a task. A firm substitutes software for staff and the wage line disappears, but the value does not show up in an equally taxable form.
So the coming fiscal shock is not only that the tax base gets smaller. It is that value increasingly takes forms the fiscal apparatus was never built to see. You cannot set a rate on a base you cannot observe. The trap tightens from the revenue side in a way no rate change can reach, because the instrument that made rates enforceable was the wage, and the wage is thinning.
This is why the deficit debate keeps feeling both urgent and strangely stale. It is trying to solve a sensor failure with rate changes.
The official numbers largely assume this away. The Congressional Budget Office’s latest ten-year baseline still expects individual income and payroll taxes to hold at between 82 and 84 percent of federal receipts straight through 2036 [6], and under ordinary macroeconomic assumptions that is a defensible call. But it means the scorekeeper’s central case is that the wage sensor keeps working exactly as it has for a century. None of this says the decay is already visible in the receipts. It is not, and the early-2020s labor data is too contaminated to read cleanly either way. The narrower claim is the one that bites: every deficit projection, every debt-to-GDP curve, every fiscal cliff we argue about inherits the assumption that it will keep working. If it is wrong, it is not wrong at the margin. It is wrong about the one input the entire forecast is built on. The baseline cannot price the possibility that the base itself becomes unreadable, because its models have no way to represent a measurement layer that decays. That is not reassurance. That is the risk, sitting unpriced inside the official numbers.
Why the usual menu misses
None of the standard answers is foolish. Each is just aimed one layer too high.
Growth is the most seductive, and it is not wrong. Growing the denominator faster than the debt reprices is the one durable exit, and every serious account of this trap, this sprint’s included, ends there. But growth answers the denominator, and revenue is a numerator problem. A productivity boom does not rescue the sensor, because it accrues where the sensor is weakest: output can rise while the taxable-at-source share of it falls. The official baseline concedes as much from the other side, quietly assuming a productivity lift from AI while still treating the wage sensor as if it will read the machine economy exactly as it read the wage one. You can grow the economy and blind the tax state in the same decade.
This is also why the optimistic AI-growth story does not remove the problem. Suppose artificial intelligence helps push the United States toward a forty-trillion-dollar economy over the next generation, or even higher if the most aggressive productivity forecasts prove right. That would ease the denominator of the debt ratio, but it would not automatically repair the numerator. If the new output arrives as wages, the old fiscal state survives. If it arrives as cloud margin, model rent, equity appreciation, automated enterprise surplus, and offshore-booked software profit, America can become richer while the tax state becomes blinder. Growth solves the denominator. It does not automatically solve the sensor.
Taxing the rich runs into arithmetic and administration. Even aggressive high-income proposals raise limited revenue relative to the long-run fiscal gap [3], and they press on the visible, realized, domestic base, which is exactly the base most able to defer, reclassify, litigate, borrow against, or leave. It is leaning harder on the part of the economy most trained in becoming hard to see.
Entitlement reform is real and, on the spending side, unavoidable. But it does nothing for revenue legibility. It slows the outflow. It does not restore the state’s sight.
Debt brakes and fiscal commissions impose discipline on a base that is going dark. A rule that forces balance is only ever as good as the revenue it can actually see. And interest compounds all of it: net interest on the public debt has now crossed the trillion-dollar line for the first time and overtaken defense as a federal spending category [4]. Rising interest on a shrinking legible base is simply the trap closing on schedule.
Behind all five is the same unexamined premise: a working sensor. Remove that premise and the entire debate is being conducted about the wrong variable.
There is a sharper point hiding in this, and it should unsettle anyone who trusts markets. A tax code that reads wages precisely but cannot read compute is not neutral, and it is not pro-market. It is a standing subsidy for whichever form of value becomes hardest to see. Left alone, the system will quietly privilege machine-mediated output over human-mediated work, not by anyone’s design but by blindness. That is not the market deciding. It is a thumb on the scale in favor of whatever hides best from the tax collector.
The state has not lost money. It has lost position.
Put the diagnosis plainly. The fiscal trap is downstream of a measurement failure.
For a century, the private economy reported itself through payroll. The employer was the state’s unofficial fiscal interface, converting millions of private transactions into one legible public stream before the individual was ever paid.
That arrangement was historically contingent. It depended on mass employment, large firms, standardized wages, and income arriving in forms that could be captured before the individual received it. The modern tax state did not merely tax labor. It was built around labor as the reporting layer of capitalism. If that reporting layer thins, the state does not merely need a new rate. It needs a new interface.
Artificial intelligence threatens that arrangement not by eliminating work overnight but by changing where the marginal dollar appears. It may not arrive as a salary at all, but as cloud margin, software rent, equity, or a task an agent completes without ever entering payroll.
The deficit is the symptom the models can see. The blindness is the disease they cannot.
Which reframes the escape. The task is not to press harder on what remains visible. It is to rebuild the instrument that decides what is visible at all.
Where value becomes visible again
There is one honest answer to where post-labor value can still be seen, and it is physical.
Compute.
Compute is the rarest thing in the new economy: value that is already metered. Every training run and every inference call is counted, because counting is how the service is billed. The meter is not a policy anyone has to invent. It is already running, humming in the data center, because the product cannot be sold without it. Compute is not just infrastructure. It is the reporting layer of machine production.
And unlike capital income, compute is anchored. A data center is bound to a grid interconnection, a water supply, a parcel of land, and a latency envelope. It behaves less like a bank account and more like a mine, a railroad, or a port: expensive to build, slow to move, locally permitted, publicly visible, and dependent on physical infrastructure. This is the same lesson the monetary essays in this sprint reach from the other side. Money is a claim that ultimately rests on a physical constraint stack. A base can be made to feel weightless for a while, but the constraint underneath does not repeal, it only waits. Compute is where that stack surfaces in the AI economy and becomes countable. The physical anchoring is not a detail. It is what makes the value both legible and harder to route away.
US data centers already consume a material and rising share of national electricity. The Department of Energy’s 2024 data center report, produced by Lawrence Berkeley National Laboratory, estimated that data centers consumed about 4.4 percent of US electricity in 2023, with demand projected to rise sharply by 2028 [5]. That is not yet a full tax base. But it is a map of where the new taxable surface is forming.
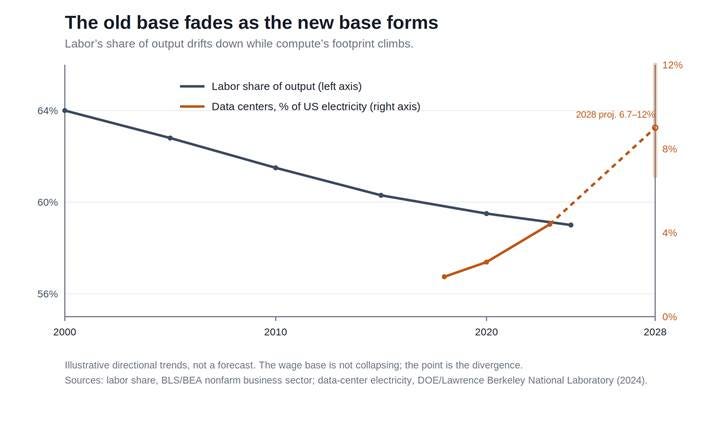
The successor to payroll withholding is therefore not exotic. It is the same architecture applied one layer higher.
The employer withheld against the wage. The compute provider should withhold against machine output.
Federal Compute Withholding
The policy should be called what it is: Federal Compute Withholding, the successor to payroll withholding for the machine economy.
Not a robot tax. Not a wealth tax. Not a punitive AI tax. A withholding regime.
And before it is a revenue measure, it is an institutional move. Payroll withholding made wages visible decades before anyone fought over the rate. Federal Compute Withholding does the same for machine output. It builds the eye first, while the base is still concentrated, physical, and counted, so the country is not forced into a panic tax after the base has already fragmented.
A robot tax fails because nobody can define the robot. A wealth tax chases a base engineered to be mobile, contested, and litigated. A general corporate tax still waits for profit to be declared after the value has passed through accounting, geography, debt, transfer pricing, and timing.
Federal Compute Withholding would collect at the layer where the value is already counted.
The basic design is simple.
First, the collection point should be the provider, not the user. Hyperscale cloud firms, AI infrastructure providers, and large model-serving platforms already meter training and inference for billing. They know how many accelerator-hours are sold, how much inference is served, which customers are using capacity, and where the service is being delivered. They are the closest functional equivalent to the employer in the payroll system.
Second, the base should begin with high-scale AI compute services above a threshold. The regime should not touch a graduate student fine-tuning a model, a small startup buying modest cloud credits, or a university lab. It should apply to providers selling or internally deploying large-scale training and inference capacity above a defined annual threshold. Start where the market is concentrated and legible.
Third, the measurement should use a hybrid safe-harbor system: AI compute service revenue where available, accelerator-hours where revenue is bundled, and energy-adjusted capacity where internal deployment makes revenue hard to observe. The perfect unit does not exist, but the payroll tax did not require perfect measurement of human value either. It required a durable reporting point. Compute has one.
A few concrete cases fix the boundary. A frontier model sold through a hyperscaler’s cloud, an API call billed through Azure or Bedrock, is covered as AI compute service revenue, metered the way the provider already bills it. A hyperscaler serving its own model internally, where no arm’s-length price exists, is covered through the accelerator-hour safe harbor. A startup below the threshold, a university lab, an ordinary SaaS product with an incidental AI feature, and consumer or gaming hardware fall outside the regime entirely. National-security and sovereign deployments sit under an explicit carve-out, so the exemption is a decision the state makes rather than a hole the base falls through.
Fourth, the rate should begin low and adjust only when the wage sensor weakens. The purpose is not to punish AI adoption. A starting levy in the low single digits on covered AI compute services would be enough to build the reporting infrastructure without strangling the sector. The rate would rise only on a defined trigger, a rolling multi-year index of labor income as a share of national output, so the levy tracks the measured erosion of the wage base rather than anyone’s forecast of it. If the wage sensor holds, the levy stays near zero. The tax activates as replacement, not as panic.
Fifth, sourcing should follow the market served, not merely the legal address of the invoice. If a model serves US users, substitutes for US labor, or is deployed by a US business into the US market, routing the billing entity through Ireland or Singapore should not erase the meter. This is the lesson the tax state learned too late from digital advertising, intellectual property, and platform profits. Build source rules before the base learns to disappear.
Sixth, the revenue should be used to lighten the tax on work, not to fund a new program. The cleanest version routes compute receipts directly against the payroll tax: for every dollar collected from covered AI compute, one dollar reduces payroll taxes on human labor, as close to dollar for dollar as the numbers allow. This is not a new spending stream dressed up as a trust fund. It is a transfer of the tax base itself, off the decaying wage sensor and onto the compute sensor, at something near revenue neutrality.
It also inverts the politics. A compute levy framed as punishment invites a fight. A compute levy that visibly cuts the payroll tax on every working American is a different proposition, and a far more durable one. The first rule of fiscal adaptation should be simple: do not tax the worker harder because the machine became harder to see. The point is not to grow the state. It is to stop taxing the thing that is disappearing and start reading the thing that is not.
This is the missing institutional move. Do not wait for AI value to become profit, compensation, or capital gains. Collect a small share when it passes through the only layer where it is still counted out loud.
How Congress could build it
Phase one is reporting first, with the tax near zero. Large AI compute providers would report covered training, inference, accelerator-hours, energy-adjusted capacity, internal deployment, and the market served. This is the payroll-reporting moment: before the country argues over how much to collect, it establishes where the new base is.
Phase two is low withholding above a high threshold. A one to three percent levy begins only for providers selling or internally deploying high-scale AI compute, with clear exemptions for research, universities, small startups, ordinary SaaS features, consumer hardware, and national-security deployments.
Phase three is the payroll offset. Receipts automatically reduce employer-side payroll taxes, worker payroll taxes, or both. The political promise should be visible on the paystub: machine-output receipts buy down the tax on human labor. The rule is simple to say and hard to argue with. Do not tax the worker harder because the machine became harder to see.
Phase four is triggered scaling. If labor income falls as a share of national output over a rolling multi-year period, the compute rate rises within a statutory band. If the wage sensor holds, the rate stays low. The mechanism activates as replacement, not as panic.
How much could it matter?
No single reform closes the fiscal gap. But every durable fiscal regime begins by finding the base it can actually see. Payroll withholding did not matter because its first year was large. It mattered because the state attached itself to the measurement layer that would dominate the next century. Compute withholding is the equivalent institutional move for the machine economy.
At the early sensor stage, suppose covered AI compute services reach one trillion dollars in annual value in the 2030s. A three percent withholding rate raises about thirty billion dollars a year, enough to fund a visible payroll-tax cut without raising a single rate on a worker. That is the floor, not the point.
At mature machine-economy scale, the base changes. If covered AI compute and machine-output services reach three trillion dollars in the 2030s, a five percent rate raises on the order of one hundred and fifty billion dollars a year, and closer to two hundred billion at the aggressive end of the statutory band. That is not a rounding error dressed up as a reform. One hundred and fifty billion is roughly a full percentage point off the combined payroll tax, a cut every worker would see on a paystub. It is on the order of a twelfth of the federal deficit, and a real bite out of net interest, the fastest-growing line in the budget, drawn from a base that did not exist twenty years ago. And if AI value scales the way its own boosters project, the base and the levy scale with it inside the statutory band, without anyone having to invent a new tax.
And if AI really is one of the engines of a forty-trillion-dollar American economy, the stakes rise again. Such growth does not rescue the tax state if the marginal trillion is formed outside payroll and booked through compute-mediated rents. In that world, failing to meter the compute layer would be one of the great fiscal mistakes in American history: a larger economy passing through a smaller fiscal aperture.
The important number is not the first-year levy. It is the claim on the next dominant tax base before that base becomes as mobile, litigated, and offshore as digital profits became. The fiscal mistake America should not repeat is waiting until a new economy has matured, fragmented, and lawyered itself away from the tax system before trying to see it.
The income tax could rely on payroll because payroll was already institutionalized when the modern state scaled. The digital economy was allowed to mature first, and only afterward did the state grasp how completely profit could be shifted and booked away from where the value was made. Ireland is the monument to that delay: a handful of American firms now route global profits through Irish subsidiaries, and a large share of the state’s corporate-tax revenue rests on the booking decisions of just a few of them. Compute is still early enough to be instrumented before it learns the same trick.
The point is not that compute is already as large as payroll. It is that payroll was once just a mechanism too. The fiscal state became powerful when it attached itself to the dominant measurement layer of the economy. If the dominant measurement layer moves, fiscal capacity has to move with it.
The objections that actually bite
Compute is mobile too.
Less than capital. An income stream can be booked in Dublin from a laptop. A training cluster cannot serve a latency-sensitive American market from a jurisdiction with no power, no grid connection, no land, and no proximity. Inference can move across borders, but not frictionlessly and not without performance, regulatory, security, and energy constraints. The anchor is the whole point. It is a stronger anchor than any the income tax has left. And where inference does move, the meter follows the market rather than the invoice. A firm can train in Virginia and route its API calls through a cheaper cluster abroad, but if the model serves US users the receipt is sourced to the US regardless of which data center answers the request, fixed by provider attestation of the served market and backstopped by the physical footprint of training. The routing is visible to whichever provider bills for it. The state’s task is only to require that the provider report it, the way an employer reports a wage.
This taxes the frontier and slows the thing driving growth.
A genuine tension. The design has to respect it: low initial rates, high thresholds, exemptions for research and small operators, and automatic adjustment tied to actual payroll erosion rather than ideological hostility to AI. But the counterfactual is not a world with no tax. It is a revenue collapse that arrives regardless and forces cruder instruments under worse conditions. Better a small meter built early than a panic tax built late.
The incidence falls on users, not owners.
Partly, yes. So did payroll. The first question a fiscal instrument has to answer is not who ultimately bears the cost in a textbook model. It is whether the state can see the value at all. Visibility comes before incidence, because without visibility there is nothing to allocate. Distribution can be corrected downstream. Blindness cannot.
This is a gross-receipts tax, and economists are right to dislike those.
Fair, and worth meeting head on. A levy on compute turnover can cascade the way gross-receipts taxes do, and charging revenue rather than margin sits heavier on low-margin, compute-heavy uses than a profits tax would. The design can blunt this by crediting the compute a provider buys in against the compute it sells, taxing the value added at each layer instead of stacking the charge layer on layer, which is how every value-added tax in the OECD already avoids this exact problem. But the deeper answer is that the honest alternative is not a clean profits tax that reaches this value. It is a profits tax that keeps missing it, because the value is shifted, deferred, and booked elsewhere before any profit is declared. A blunt instrument aimed at a base you can see beats an elegant one aimed at a base you cannot. Payroll was blunt too, and it funded the modern state anyway.
Measuring value at the compute layer is hard.
It is the one place it is least hard. Raw compute is an imperfect proxy for value, but it is measured more reliably than most of the capital income the tax state currently tries to chase. Tokens, accelerator-hours, energy draw, utilization, and model-serving revenue are not metaphors. They are operational quantities. The state does not need metaphysical precision. It needs a durable withholding point.
If the Wage Sensor Holds
The bet is straightforward: wage income is losing, or may soon lose, its place as the base the state can most easily see. If labor income stabilizes, payroll receipts hold through the 2030s, AI value flows back into wages faster than it leaves them, and inference decentralizes so completely that no metering chokepoint remains, then Federal Compute Withholding is not the next fiscal layer. The old one survived.
But a temporary burst of payroll revenue during a data-center construction boom would not prove that. It would be the old sensor at its brightest moment, not evidence that it can read the machine economy after construction gives way to operation. Nor would it refute the proposal to say compute withholding cannot replace the whole tax system. Payroll withholding did not abolish every other tax. It made the modern revenue state administratively possible.
That is the standard here. Not omnipotence. Institutional succession. If payroll was the fiscal interface of industrial capitalism, compute is the most plausible fiscal interface of machine production.
The escape
The escape from the fiscal trap is usually pictured as a hard choice finally made: the grand bargain, the ceiling held, the entitlement cut nobody wanted, the tax increase nobody wanted to vote for. Some version of those choices may still be necessary. But a decision about the rate is worthless if the state can no longer see the base. This is why Federal Compute Withholding belongs at the center of the fiscal conversation, not at its edge: it is the instrument that makes every later bargain possible in a machine economy.
America’s fiscal problem is therefore not only budgetary. It is institutional. The tax state was built for an economy where value passed through wages before it passed into consumption, savings, or capital. Artificial intelligence is building an economy where more value passes through compute before it ever becomes payroll at all.
The old fiscal state read wages. The new one has to read compute.
That does not mean strangling AI. It means recognizing the obvious fiscal fact hiding inside the technical one: the machine economy already meters itself. It counts its training runs, its inference calls, its accelerator-hours, its energy draw, its utilization, and its capacity. The state does not need to invent a new eye. It needs to stand where the economy is already looking.
This is the choice underneath the arithmetic. A small meter built early, while the base is still legible, is renewal. A crude tax improvised late, under fiscal duress, is managed decline. The base is moving either way. The only open question is whether the state reorients in time to see where it went, and whether it uses that new sight to reduce the tax burden on human labor before the wage base thins.
The United States has a spending problem and a revenue problem both. Underneath them is the one almost no plan prices: a seeing problem.
The escape begins by building the meter before the base disappears.
Notes
[1] Congressional Budget Office, Revenues in Fiscal Year 2024: An Infographic. CBO reports $2.426 trillion in individual income taxes and $1.709 trillion in payroll taxes out of roughly $4.9 trillion in total federal revenue for FY2024 (about 84 percent combined). FY2025 figures confirm the pattern: about $5.2 trillion in total receipts, a $1.8 trillion deficit (5.9 percent of GDP), with individual income and payroll taxes still supplying the large majority of revenue. The combined share dips slightly in FY2025 only because tariff receipts surged. CBO’s forward baseline holds it at 82 to 84 percent through 2036 (see note 6).
[2] OECD, Revenue Statistics 2025. Personal income tax and social security contributions together make up roughly half of total OECD tax revenue.
[3] Brookings Institution, “Can Taxes Alone Fix Long-Term Deficits?” (2026), finds that even an aggressive combination of high-income and corporate measures (taxing capital gains as ordinary income, a 77 percent estate-tax rate, a 35 percent corporate rate, and applying Social Security tax to all earnings) falls well short of the roughly 4 to 5 percent of GDP adjustment needed to stabilize the debt, and that closing the gap on the revenue side requires broad-based taxes reaching well beyond high earners. Manhattan Institute (Jessica Riedl), “The Limits of Taxing the Rich,” reaches the same conclusion from the revenue-maximizing side: taxing the wealthy at revenue-maximizing rates yields at most about 2 percent of GDP, and roughly 1 to 2 percent after accounting for macroeconomic responses.
[4] Congressional Budget Office, Monthly Budget Review: Summary for Fiscal Year 2025. CBO reports that net interest on the public debt surpassed $1 trillion for the first time in FY2025; independent analyses note it now exceeds national defense spending by roughly $150 billion.
[5] Department of Energy / Lawrence Berkeley National Laboratory, 2024 United States Data Center Energy Usage Report. The report estimates data centers consumed about 4.4 percent of US electricity in 2023 and projects data center demand could roughly double or triple by 2028.
[6] Congressional Budget Office, The Budget and Economic Outlook: 2026 to 2036 (February 2026). CBO projects that individual income and payroll taxes remain between roughly 82 and 84 percent of federal receipts through FY2036. As summarized by the Bipartisan Policy Center, “The Fiscal Outlook in CBO’s Latest 10-Year Baseline” (February 11, 2026).
This article is a practical solution for a looming situation and thank you for making it legible even for a non-economist.
The analyis is sound but the policy conclusion is not. There is no need to invent an alternative to taxing income and less to taxing only wage income; it has already been invented: taxing consumption (income - saving/investment). If we were totally indifferent to tax regresivity, we could raise all revenut witha VAT. I think we sholld not be indifferent and so think we should also tax personal consumption at progressive rates, greater consumption, hgher rates.